

With copper rebounding back above US$6/lb, there couldn’t be a better time to review Robert Friedland’s keynote presentation from earlier this year at the 35th Annual BMO Global Mining, Metals & Critical Minerals Conference in Hollywood, Florida. Then we’ll discuss an interview of Rick Rule on Adam Taggart’s “Thoughtful Money” podcast.
Copper (Weekly)
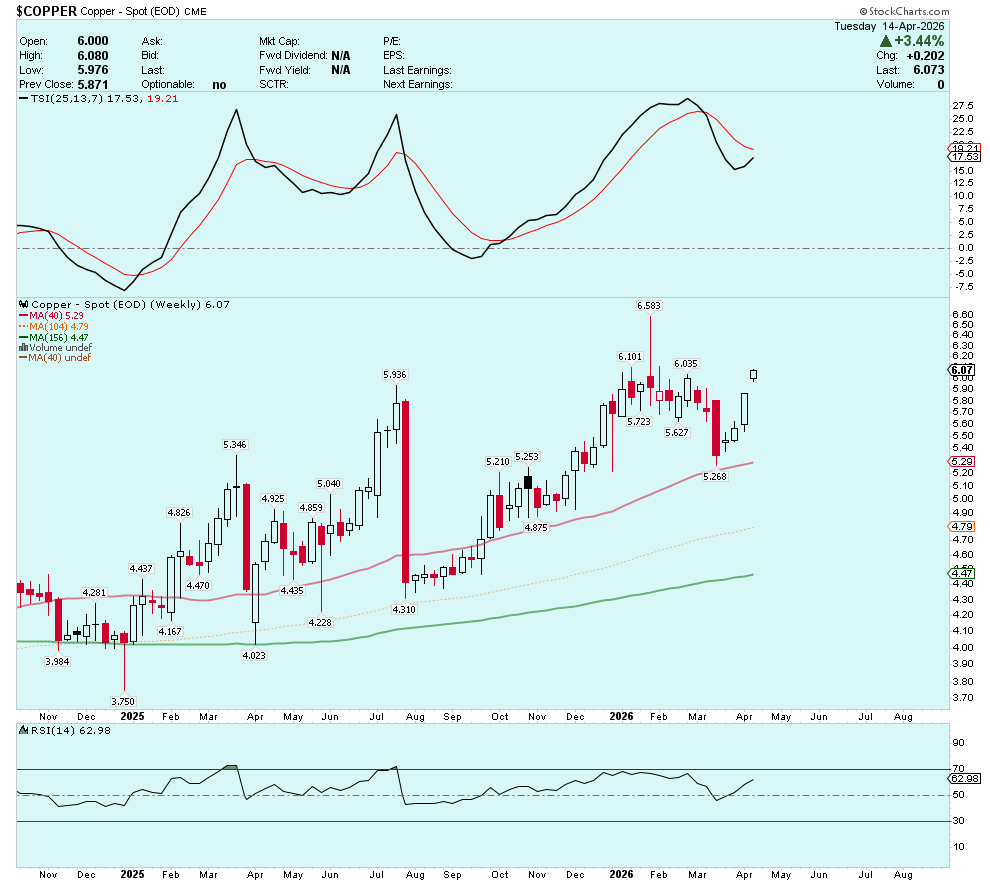
If the week ended today, copper would register a new all-time weekly closing high. Copper has spent very little time above $6/lb, so if it can hold this level through the next 72 hours, it would be highly meaningful.
The rise of data centers, Artificial Intelligence, and reindustrialization has created significant demand for critical minerals and essential industrial metals like copper. Meanwhile, geopolitical tensions could impede the industry’s ability to meet growing demand. Combine these issues with structural problems around how mines are approved, financed and developed, and supply could be further constrained.
For example, Chinese authorities have announced that China will not be allowed to export sulphuric acid from next month. China is effectively shutting off sulphuric acid exports starting next month, aside from electronic-grade material. That removes a major source of global supply at a time when Middle East disruption is already tightening sulphur and acid markets.
That is near-term bullish for copper.
A few highlights from Friedland’s keynote presentation:
The AI revolution uses copper
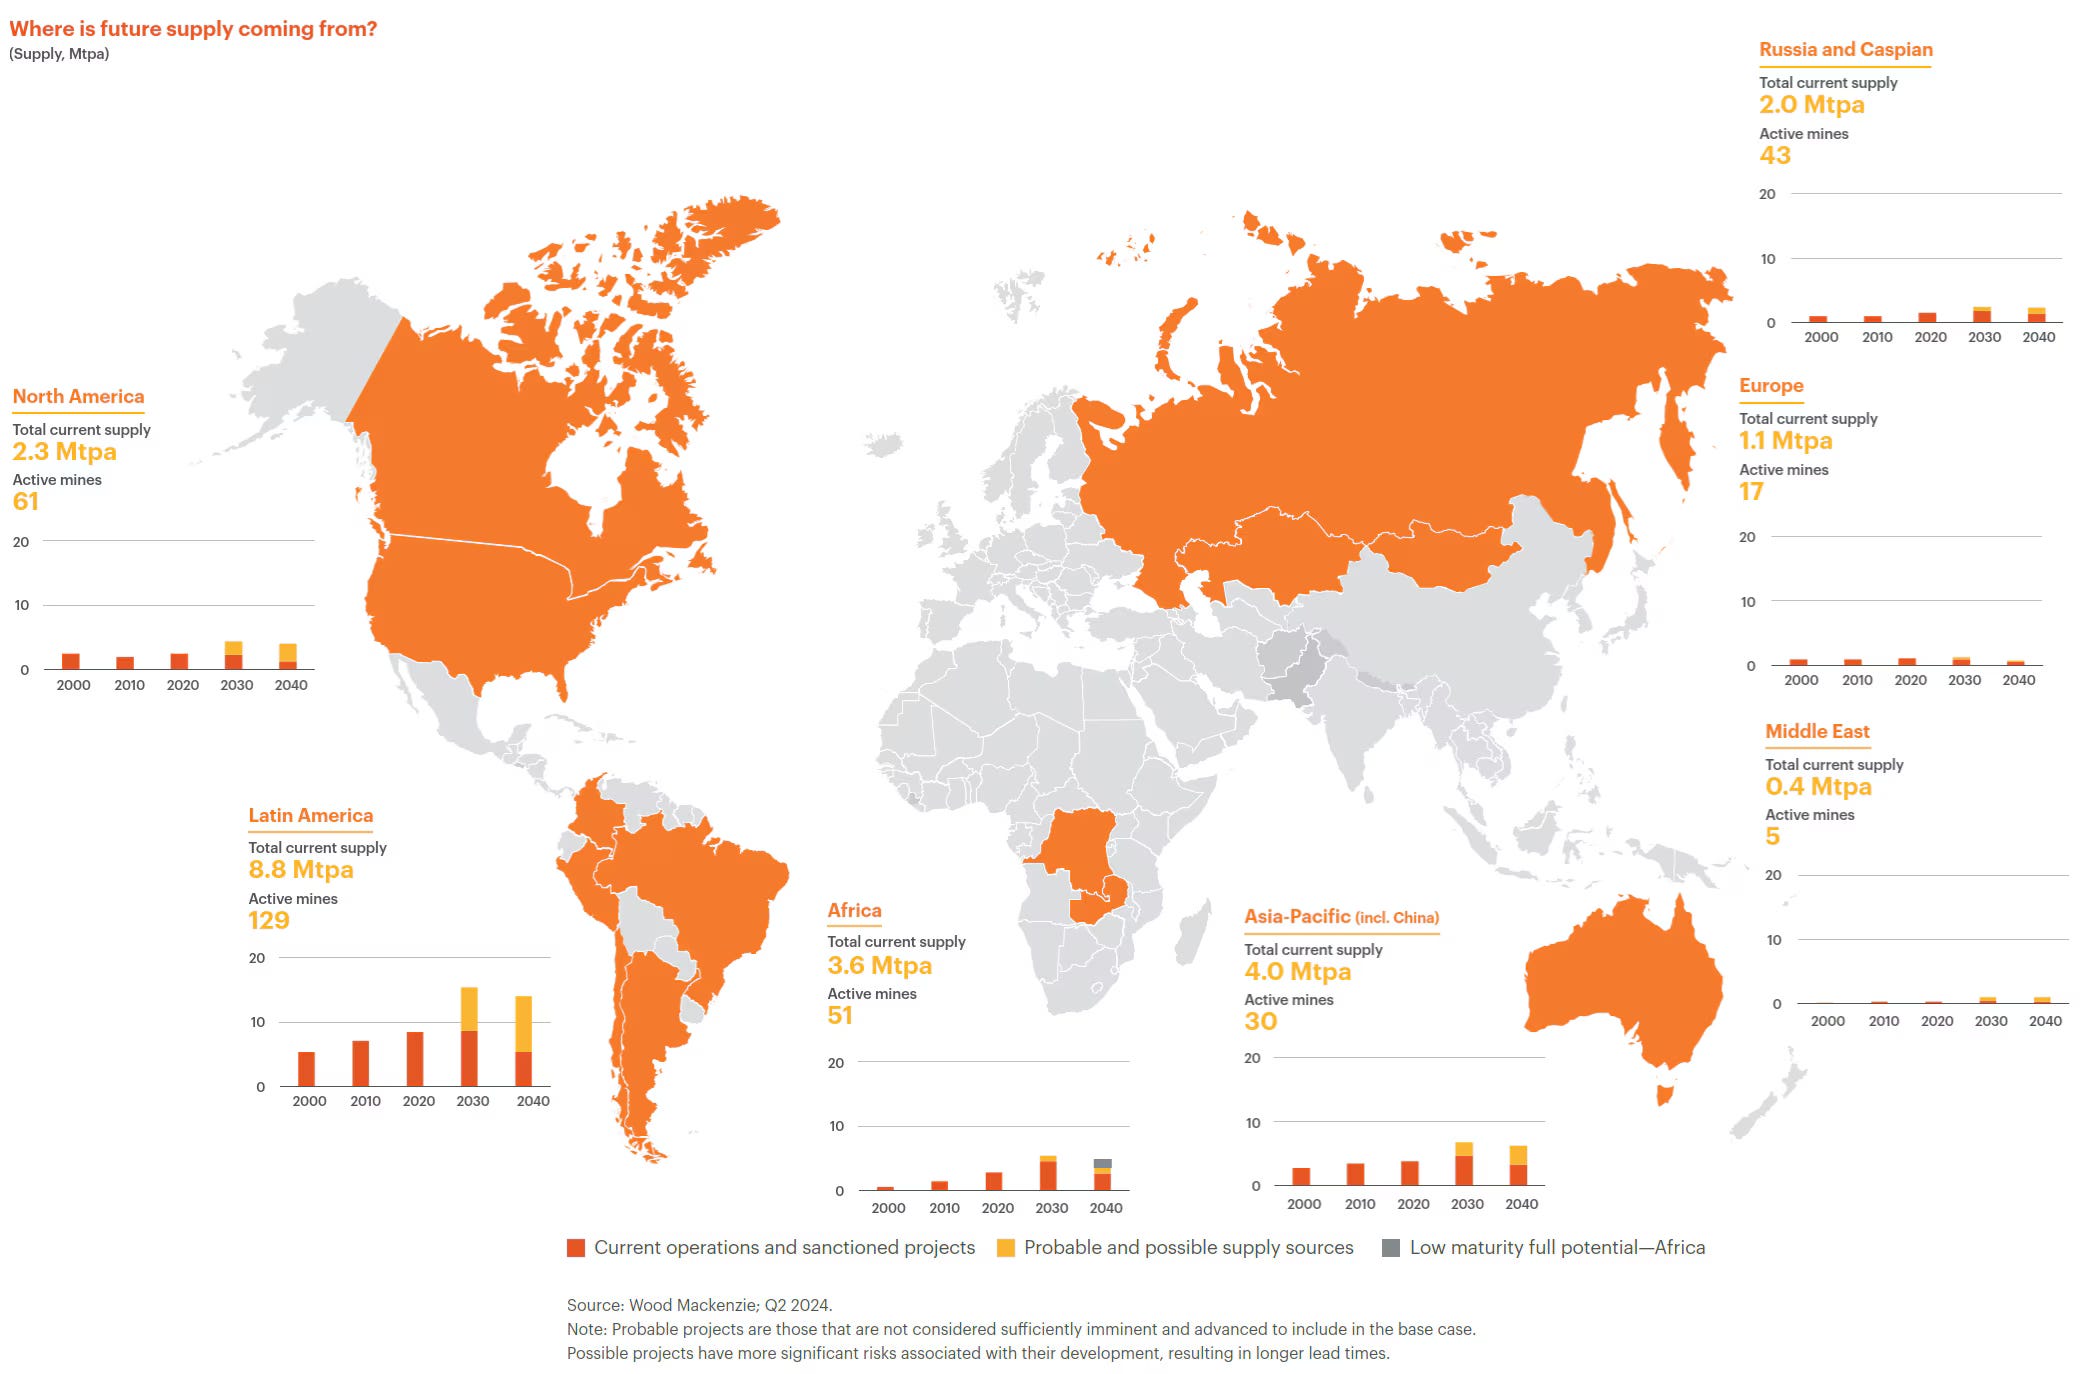
While the need for copper has been steadily increasing for years, the emergence of generative AI and the rapid expansion of data centers have taken demand to a new level. A 500-megawatt data center would require a lot of copper, along with a group of other rare-earth materials and critical metals such as barium, antimony, titanium, indium, silver, tungsten, gold, gallium and palladium.
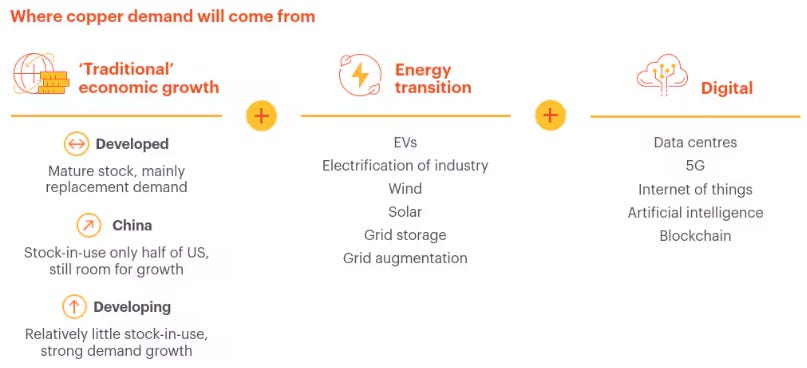
When combined with defense and other needs, Friedland said the world needs to add multiple new tier-one copper mines annually to meet global demand, specifically supporting electrification, data centers and the revitalization of the grid. “The deficit is real,” he said.
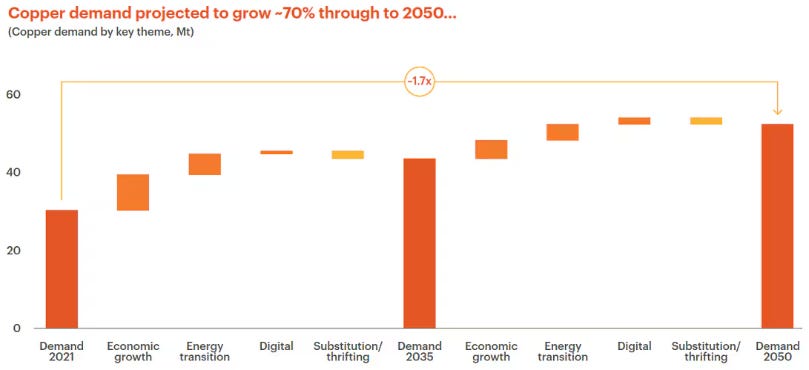
To put that in context, the amount of copper required in the next 18 years to meet expected demand is equal to all the copper that’s ever been mined so far – an estimated 700 million metric tonnes, added Friedland.
Critical mineral supply chain at risk
As the industry works to determine where the global economy will source the metals and critical minerals it needs, there is growing concern that supply chains are vulnerable to geopolitical tensions and require diversification.
Today, the critical minerals supply chain is concentrated in China. “We don’t have an economy without those metals,” said Friedland. “There’s a growing global recognition that we need to have supply chains for critical minerals that are reliable and diverse across the world.”
He singled out aluminum-scandium alloy. Not only is the material a leading candidate for next-generation memory chips, but it’s also promising for the future of 6G wireless communication, defense and 3D printing. “I can’t possibly overemphasize how critical these metals are,” he said.
Adding supply chain resilience
Countries like China have gained a dominant role in the global supply chain in part because of the way they approve and support new mines. If a Chinese company wants to build a mine, they just ask the government for funding, said Friedland.
The U.S. is looking to follow suit. Friedland applauded the move earlier this year by the Export-Import Bank of the U.S. to launch Project Vault, a $12 billion plan to stockpile 60 critical minerals to provide economic security and strengthen industrial resilience during supply chain disruptions.
The main takeaway from Friedland’s BMO keynote was that there are real physical constraints on the future. “You can’t print mines….you can’t print real things.”
This is still a rude awakening for many in the West. Regardless of who sits in the White House or which party controls Washington, the urgency of securing and rebuilding the raw materials supply chain cannot be ignored. We are at the starting line of a global race for critical minerals, and supply chains are shifting from “just in time” to “just in case.” It will be a long, friction-filled process that demands enormous capital investment.
Rick Rule: The Coming Copper Price Shock
According to legendary natural resources investor Rick Rule, the world has under-invested in copper production for so long that "there's nothing we can do" to avoid the copper price rising to the point where rationing begins.
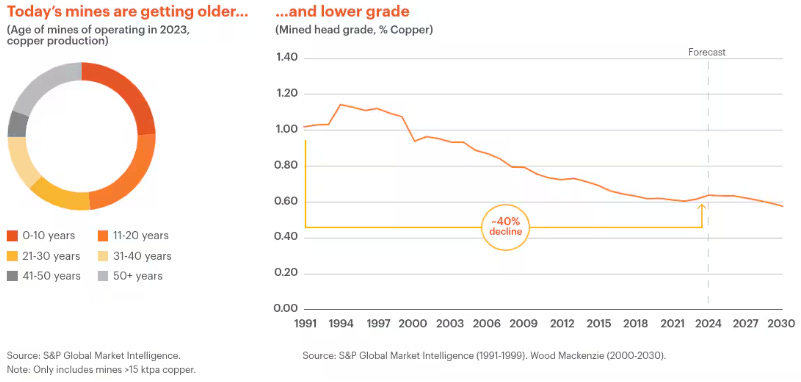
“We have underinvested in copper, in all phases of copper for 30 years. We’ve underinvested in exploration. We’ve underinvested in permitting. We’ve underinvested in process and technology. We’ve underinvested in mine construction. And this is a capital intensive business with very very very long lead times.
There is nothing, Adam, that we can do as a species in the next five years that will reduce the probability that the balance of supply and demand in copper is met by rationing by price. There is nothing that we can do that will prevent the price of copper in real terms from increasing over five years to the point where copper has to be rationed by price….nothing that we can do.” ~ Rick Rule on Thoughtful Money
A powerful delivery by Mr. Rule that helps to drive home the point of just how far behind the curve the world is in terms of delivering the copper that we will consume over the coming years.
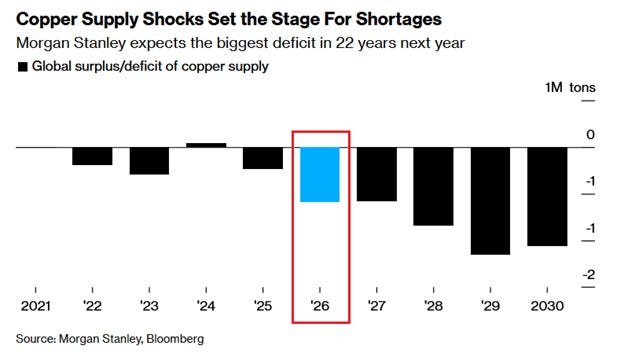
And to reemphasize just how clear, and unavoidable, the rising supply/demand deficit for copper is, Rick drives the point home…
“I think that the difference is, do we exceed past consumption in all of human history in 15 years or in 30 years?
Either way, production’s falling. It’s not increasing, right?
Production is falling.
And there is nothing we can do, nothing, not one thing that we can do to interrupt that. If we started looking for copper today, in my experience, as an example, grassroots exploration on a district scale takes a decade to pay off.
So, we go to Kazakhstan or Uzbekistan or Kyrgyzstan, somewhere in Central Asia that hasn’t been explored, but one that is very prospective for copper. We start looking. It’s likely 10 years before we find enough to make a difference.
Then we begin the process of permitting it.
In some jurisdictions that don’t actually have functioning mining laws yet. Having achieved that, we go to finance it and then we go to build it. We’re talking about a circumstance where we meaningfully increase supply from frontier areas 15 or 20 years from when we push the start button.
In other areas, a wonderful place to look for copper is the central Arizona copper belt.
Lot of copper there, trained workforce, rule of law, utilities, transportation, all that stuff. The Resolution Deposit , which we talked about at the top of this interview, a fine deposit, 1.5% copper grade in a world where the average mine grade is less than .5%.
It’s been stuck in permitting for 28 years. (FACT CHECK: Resolution has been in the formal U.S. federal permitting stage since 2013, so it’s more like 13 years).
They haven’t begun the process of building it because it hasn’t been permitted yet. There’s not one thing we can do, not one thing that we can do that meaningfully changes the balance between supply and demand in the copper business for at least 5 years, and probably 10 years.”
The price of copper is going higher, potentially much higher. A higher price is the most effective method of curbing demand and incentivizing new supply to come online.
“I think we will ration by price because I think the utility of copper is so high.”
Because the utility of copper is so high, demand is relatively price inelastic. That means the price of copper may have to move significantly higher before demand is meaningfully curtailed.
The secular bull market in copper is a theme Goldfinger Capital has focused on for years, yet it is still relatively early in terms of timing the bigger picture macro cycle. We will continue working to highlight value creation and discovery opportunities across copper exploration, development, production, and technology.
DISCLAIMER: The work included in this article is based on current events, technical charts, company news releases, corporate presentations and the author’s opinions. It may contain errors, and you shouldn’t make any investment decision based solely on what you read here. This publication contains forward-looking statements, including but not limited to comments regarding predictions and projections. Forward-looking statements address future events and conditions and therefore involve inherent risks and uncertainties. Actual results may differ materially from those currently anticipated in such statements. This article is provided for informational and entertainment purposes only and is not a recommendation to buy or sell any security. Always thoroughly do your own due diligence and talk to a licensed investment adviser prior to making any investment decisions. Junior resource companies can easily lose 100% of their value so read company profiles on www.SedarPlus.ca for important risk disclosures. It’s your money and your responsibility.
I attended Rick Rules 'copper bootcamp' this last weekend. Friedman reiterated his arguments, and then Rule interviewed three copper plays - the one I like best is Hot Chili. low altitude coast deposits, recent finding of higher grade core at La Verde that will likely support a starter pit and front load incremental cash flow, and cluster of deposits that can be mined from shared infrastructure. The kicker is a permit to use seawater in its mining operation and also to become a water supplier to other mines in the area (including those at altitude).
Robert ... I have a bunch of copper ... and all things metal ... I am sorry for the state of the US and the World economies ... and the $9T debt ... and the printing presses running 24/7/365 ... and the re-rating that will suck unless you own junior minors ... senior minors and hard assests ... I didn't make the Freaking mess ... but I bet I clean up ... Thank You !!